Quarterly IRS payments, explained
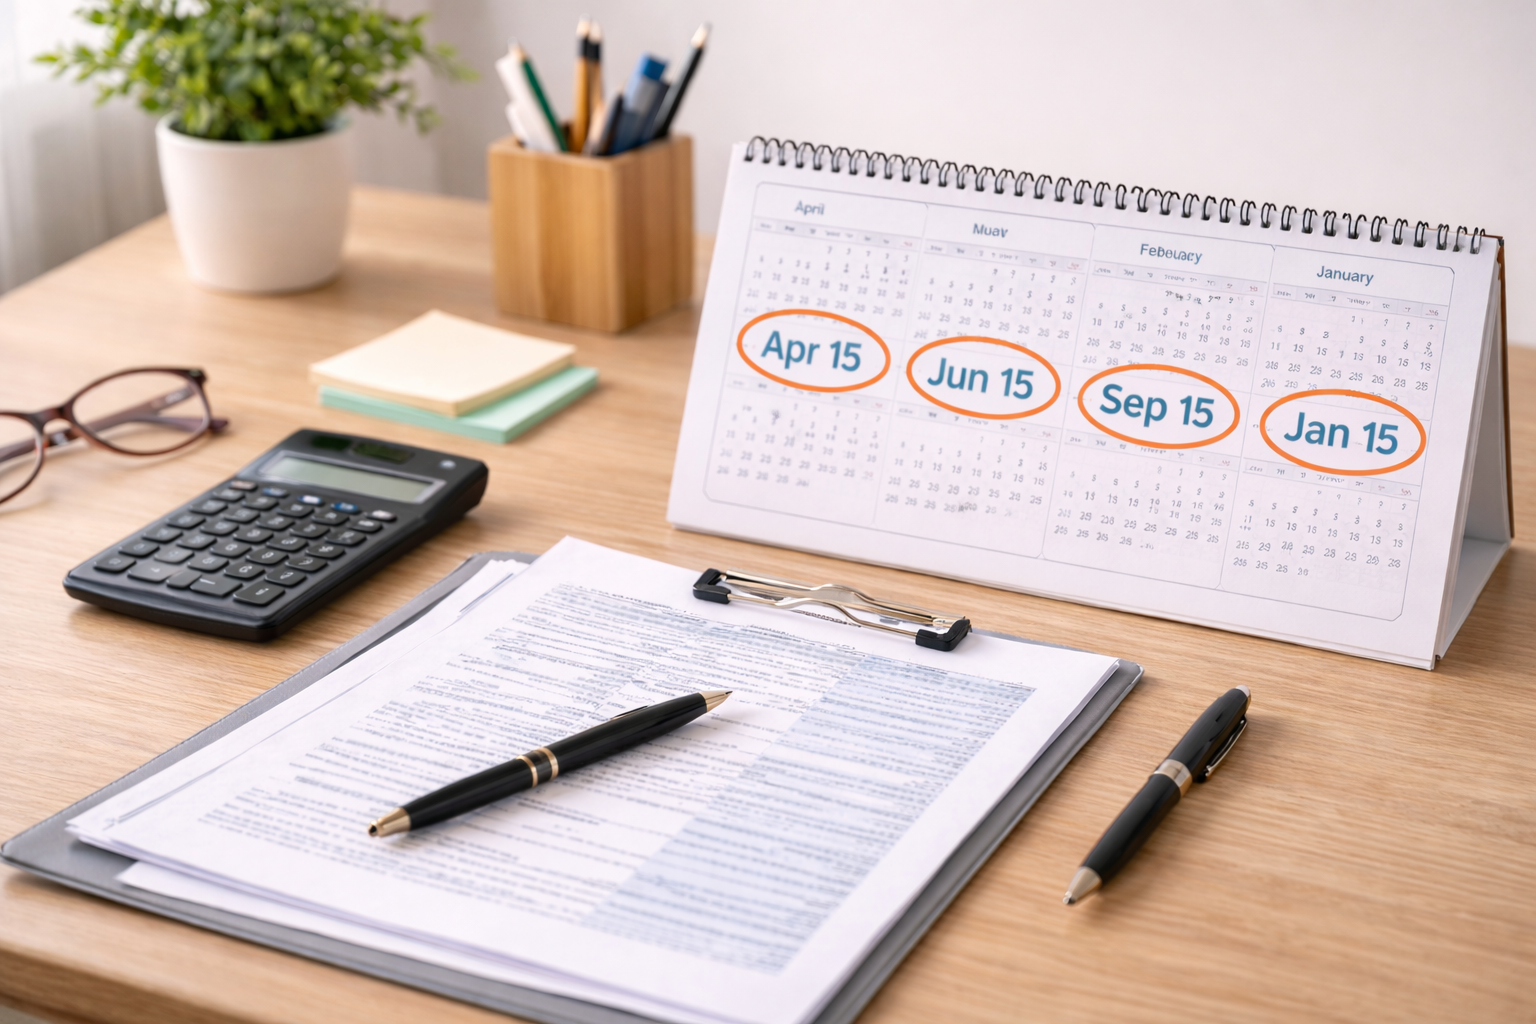
Last week, we talked about the payments that are due on April 15. However, the IRS sometimes requires people to make quarterly tax payments. These payments are due on
- April 15
- June 15*
- September 15*
- January 15
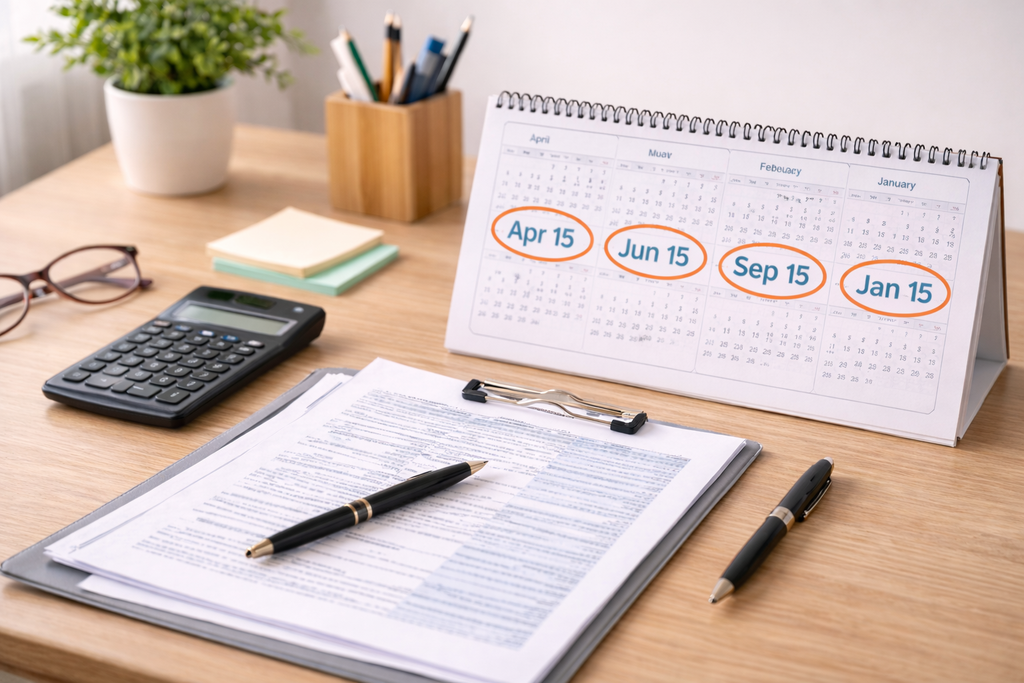
*Yes, you read those dates right. They don’t exactly coincide with the official “end of the quarter,”, but I assure you that it’s correct. That’s why they’re technically called “ES Payments.”
Generally speaking, these payments are designed so that you pay the same amount as you paid during the prior year, plus an extra 10%. That’s the IRS’s way of getting paid “in advance,” rather than just getting paid once a year on April 15. (After all, we all want to get paid sooner rather than later.)

Q: Do I really HAVE TO make those payments?
A: The answer is… not really. The IRS doesn’t say “Thou Shalt Make Thy Quarterly Payments Upon Penalty of Death.” It says “If thou makest not thy quarterly payments, then thou shalt pay interest.”
Well, technically, it’s not “interest”. It’s a “penalty” for “failure to make estimated tax payments.” But it is based on interest rates, which makes it interest, for all intents and purposes. And the rate that you pay is, by definition, about the same as the Prime Interest rate. So let’s just call it “interest”.
Here’s one way to look at it: The current interest rate (as of February 2026) is about 7%. By NOT pre-paying your taxes, the IRS is effectively lending you money at a 7% interest rate. So essentially, you’re “borrowing” from the IRS at 7%.
Or here’s another way to look at it: The interest rate is about 3% higher than you’d make on your bank CDs. So by pre-paying the IRS, you’re “losing” 3%. (Which makes perfect sense, when you think about it. After all, they want to get paid first.)
So no–you don’t HAVE TO pre-pay the IRS. It may be a good idea, but it’s certainly not imperative.
Q: But if I made all my quarterly payments last year, then I’m guaranteed to not have any penalties, right?
A: You’re guaranteed not to pay any INTEREST through April 15. However, if you’re still underpaid on April 15, then you will pay the aforementioned “1% per month” penalty for any amount due to the IRS.
Q: So you’re saying that I could make all my quarterly tax payments AND STILL OWE PENALTIES?
A: Yes–that’s exactly what I’m saying. These are two totally, distinctly different penalties.
Q: Why was my prior CPA so adamant that I pay my quarterly payments? He never told me it was optional!
A: Remember the old saying, “To man with only a hammer, everything looks like a nail.” Similarly, to a CPA whose sole purpose in life is to achieve perfect tax compliance, then he will only help you achieve “perfect tax compliance”, which may be to the detriment of other parts of your financial universe.
Q: Well, if I don’t have the money to pay my taxes, should I still file?
A: That’s a personal decision, and of course, the answer is “It depends.”
Here’s why you SHOULD make the quarterly payments:
- If you hate paying interest (regardless of who it’s to)
- If you want a “guaranteed” 7% interest rate
- If you’re a good recordkeeper and can keep the payments straight. (The April 15 payment can get tricky, because there are multiple payments due on that day, and it’s easy to get them confused.)
And here are some reasons why you should NOT make the payments:
- If you have investments that are generating higher than 7%
- If you have other debt that charges higher than 7% (although this indicates that we probably need to do some additional planning)
- If you’re a bad recordkeeper and are likely to get messed up, because it will cost more to fix the mistakes than it would to simply pay the penalties.
- If you like having money in your bank account (for emergencies or contingencies)
- Or, if you just like to keep things simple, and don’t mind paying a little interest.
Here’s another option (and this is what I do, personally).
I simply adjust my withholding from my paycheck. It works exactly like making quarterly payments, but it reduces all my recordkeeping, because it’s all reported on my W-2. I think this is the easiest, most fool-proof way to pre-pay your estimated taxes.
Here’s the final word on tax penalties – Nobody likes paying penalties. But understand–penalties are sometimes just part of doing business with the IRS. And sometimes it costs more to AVOID the penalties than the penalties themselves. Sometimes the cure is worse than the disease.
Let us know if you want to talk to us.
Start your tax savvy journey
Whether you’re ready to get started or have questions about our firm, we’re here to help.
Call Derek: (432) 687-0243
Email Derek: hello@basinwealth.com