Timing (amount and deductibility) of IRA contributions
One of the most common tax deductions that people take advantage of is the IRA – an Individual Retirement Account. Here’s how it works: You open an account with the bank or brokerage firm of your choosing. You deposit money into the account, and you can invest in anything the bank or brokerage firm offers — and you don’t have to pay taxes on the earnings until you withdraw.
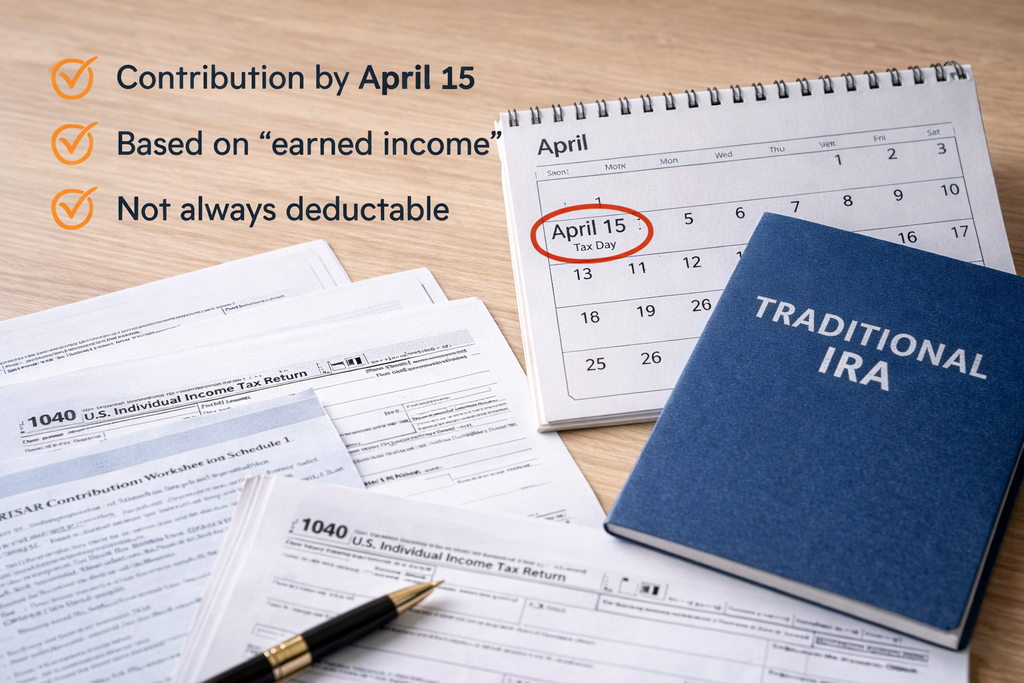
HOWEVER – there are three traps for the unwary:
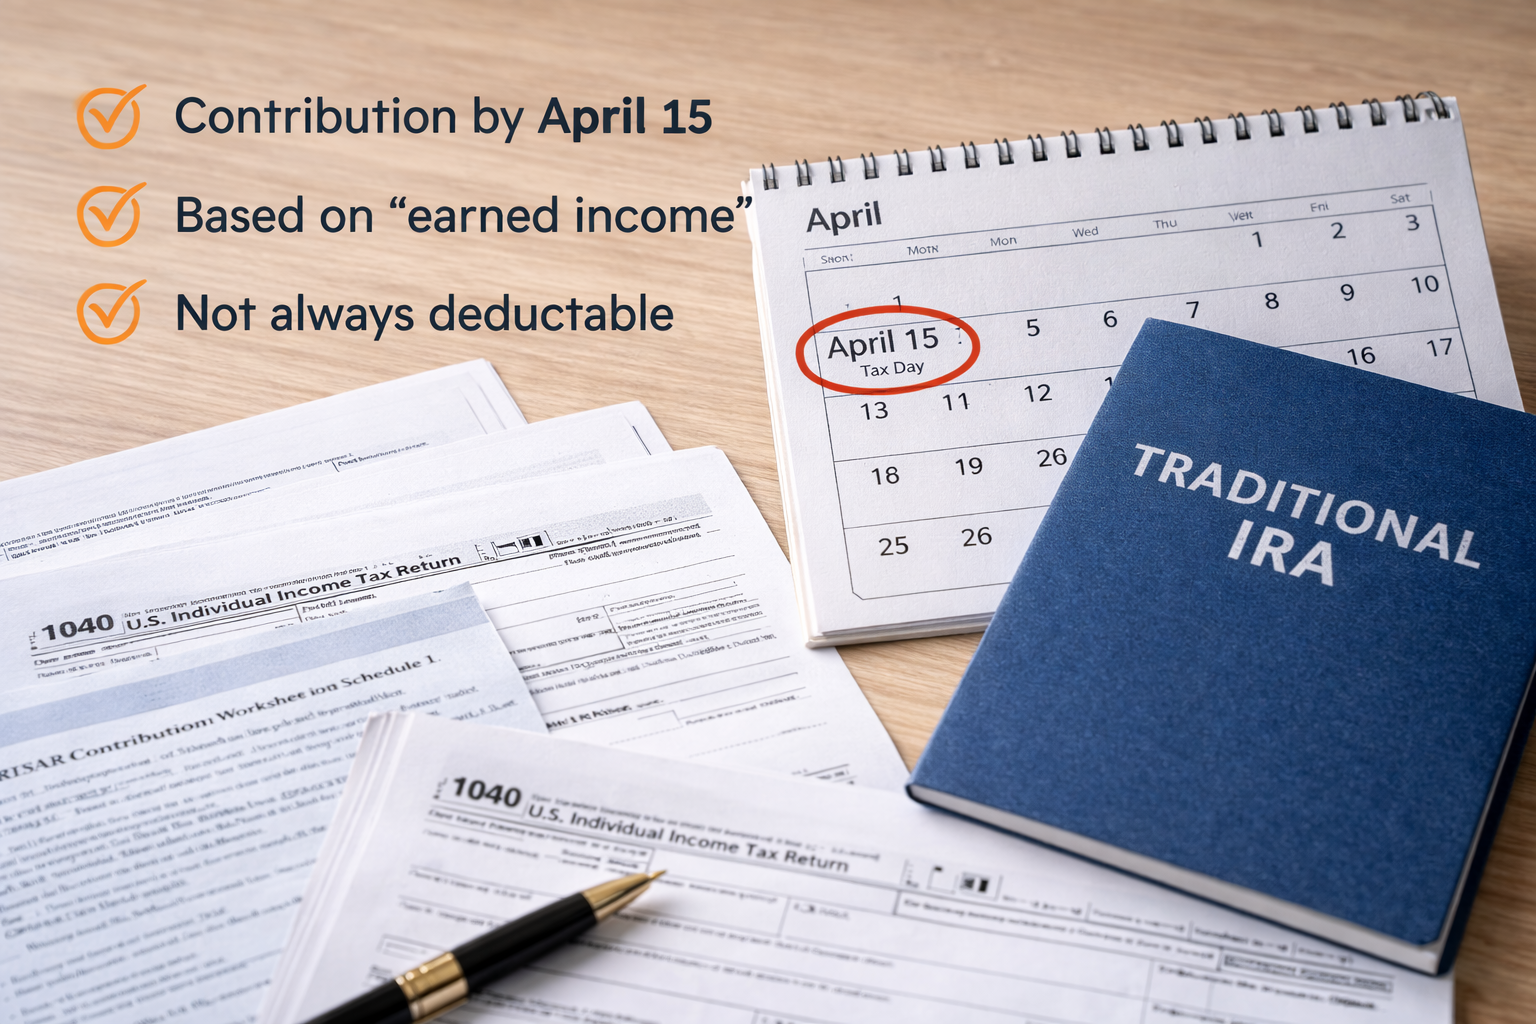
- To make a contribution for LAST YEAR, that contribution must be made by April 15. NO EXTENSIONS.
- The amount you contribute is based on your “earned income” as shown on your tax return. “Earned income” means income from working at a job, including self-employment. It does NOT include income from rents, royalties, interest, dividends, or any other income that is not directly related to working at a job.
- Not all IRA deductions are deductible. People who have retirement plans at work may not get the deduction for their IRA.
So, how do you avoid these three traps?
Simple—ask your tax preparer after your tax return is prepared, BUT BEFORE IT IS FILED.
Let me repeat that:
Ask your tax preparer AFTER YOUR RETURN IS PREPARED, BUT BEFORE IT IS FILED.
Why? Because to adequately answer these questions, the return must be prepared. However, any decisions regarding the deduction must be made before the return is filed.
So the only person who can really answer these questions is… you guessed it—your tax preparer.
No – your investment advisor CANNOT answer these questions – at least not until the tax return is prepared but NOT FILED. And even then, it requires a thorough knowledge of the tax code (and usually some specialized software).
If it sounds confusing, that’s because IT IS—even for most professionals. Many simply don’t have the expertise to advise on both TAX matters and INVESTMENT matters, and it’s often hard to get the tax preparer and investment advisor on the same page—especially during tax season.
The good news
Fortunately, this is exactly what we do at Morris Holmquest Tidwell. We are both a CPA firm and an investment advisory firm, so we can handle both simultaneously.
Note: this post discusses Traditional IRAs only. We’ll cover Roth IRAs in our next newsletter.
Start your tax savvy journey
Whether you’re ready to get started or have questions about our firm, we’re here to help.
Call Derek: (432) 687-0243
Email Derek: hello@basinwealth.com