Roth IRA contributions, explained
Last week, we discussed Traditional IRAs—the good, the bad, and the ugly. This week, we turn our attention to Roth IRA contributions.
In short, Roth IRAs are another type of retirement account for individuals. They have some similarities to—and some differences from—Traditional IRAs.
Similarities:
- They have the same IRS contribution limits. For 2025, that limit is $7,000 (plus an extra $1,000 if you’re over 50).
- They have the same eligibility requirement: you must earned income.
- You can open them anywhere, just like a Traditional IRA—banks, brokerage firms, etc.
- They have the same investment options—anything the custodian is willing to hold.
- They have the same deadline. To make a contribution for the prior year, it must be made by April 15. NO EXTENSIONS.
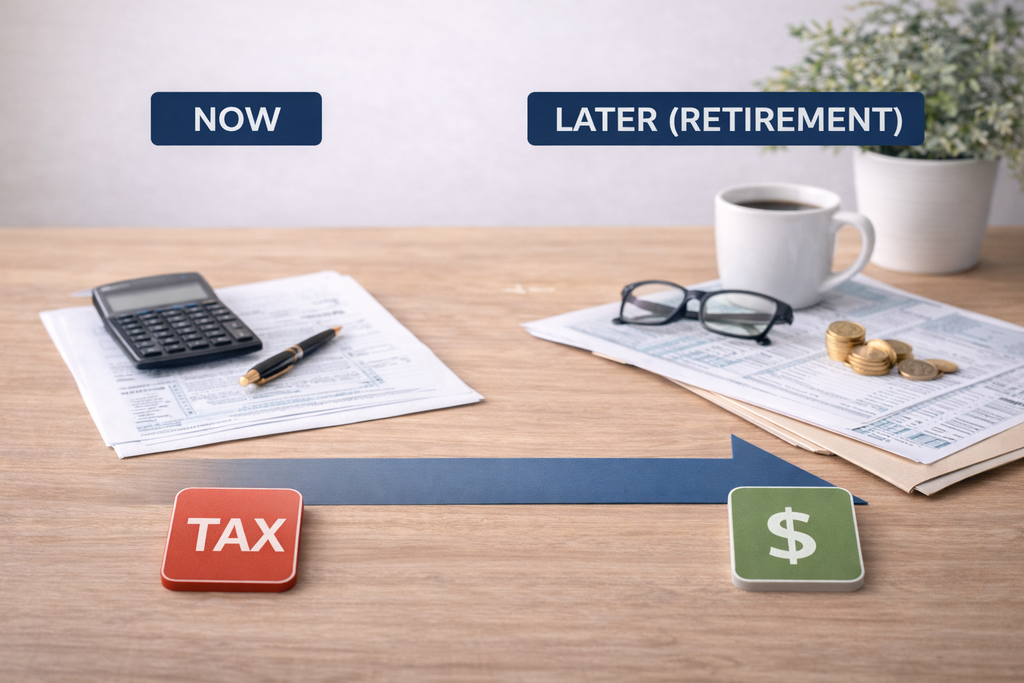
The biggest difference between Traditional and Roth IRAs is not how the account works – it’s WHEN YOU PAY THE TAX.
With Roth IRAs, you do NOT receive an immediate tax deduction. However, when you withdraw the money in the future, you generally do NOT pay tax on it either.
Unfortunately, just like their Traditional IRA brethren, Roth IRAs have a tax trap of their own: not everyone can contribute to a Roth IRA.
There are strict income limitations, and if you exceed them… you simply can’t contribute. For example:
- A married couple is ineligible if their income exceeds $252,000
- Individuals are ineligible at $168,000
Note: there is something called the “backdoor Roth,” which gets around these income limitations, but it is fraught with peril and will be discussed in a future newsletter.
So how do you know if you’re eligible for a Roth contribution?
The answer is exactly the same as it was for the question, “Can I deduct my Traditional IRA contribution?”
Consult your tax preparer AFTER YOUR RETURN IS PREPARED, BUT NOT FILED.
And the why is the same as well. In order to answer this question, the tax return must first be prepared. Only then will we know the answer. If you are ineligible to contribute, you may need to recharacterize the contribution (i.e., turn it into a Traditional IRA contribution) or withdraw it entirely.
So once again, the only person who can adequately answer these questions is your TAX PREPARER, and only after the tax return has been prepared, but not filed.
Fortunately, this is exactly what we do at Morris Holmquest Tidwell. We are both a CPA firm and an investment advisory firm, so we can handle both simultaneously.
Start your tax savvy journey
Whether you’re ready to get started or have questions about our firm, we’re here to help.
Call Derek: (432) 687-0243
Email Derek: hello@basinwealth.com